
Core inflation excludes oil. Bitcoin investors still cannot ignore it

 Prefer us on Google


Oil could remain an obstacle to lower borrowing costs and greater risk appetite among Bitcoin investors, even when energy is excluded from core inflation. A Federal Reserve staff study published Nov. 9 estimates a stronger link between oil-price changes and underlying inflation in data from 2021 onward, potentially complicating monetary easing.
The findings put numbers to a channel behind the financing risks discussed in CryptoSlate's recent diesel coverage. They describe a conditional inflation threat: the authors say second-round effects from the current oil shock have not yet materialized.
Excluding energy does not remove every fuel cost embedded in other products. The U.K.'s Office for National Statistics explains that core CPI strips out direct energy components while retaining indirect energy costs in prices such as hospitality, telecommunications and transportation. Businesses can therefore pass energy costs into prices outside the excluded categories.
The Fed researchers pooled Canada, the euro area, Japan, the United Kingdom and the United States, using data from 2000 through the second quarter of 2026. The U.S. measure is core personal consumption expenditures inflation; the others use core consumer price inflation.
For the period beginning in 2021, the model links a 10-percentage-point increase in relative oil-price inflation to a roughly 0.14-percentage-point increase in core inflation. In the pre-2021 period, the estimated response was about 0.01 percentage point and statistically insignificant.
Those units matter. Relative oil-price inflation measures quarterly changes in local-currency Brent prices relative to core inflation. A 10-percentage-point increase in that measure is different from a 10% rise in oil's price level. The model allows transmission through the current quarter and four previous quarters.
Oil can reach core prices through the costs left inside
Energy components are excluded, while indirect costs can remain. The staff model estimates a stronger oil-to-core link in the period beginning in 2021.
Oil's indirect route into core inflation A fork shows direct fuel components excluded from core and indirect costs still included. A dashed final connector marks the inferred Bitcoin risk. 01 / THE ROUTE THAT REMAINS OIL COSTSInput pressure Direct energy componentsFuel bills are excluded from core EXCLUDED Indirect costs in other pricesHospitality · telecoms · transportRemain in U.K. core CPI CORE PRICE PRESSURECan outlast the direct fuel rise IF PRESSURE PERSISTSTighter policy in the staff simulation BITCOIN INFERENCEDelayed financing relief · constrained risk appetite
Oil's indirect route into core inflation Direct energy components leave core CPI, but costs embedded in other prices remain. Bitcoin financing risk is a conditional inference. 01 / THE ROUTE THAT REMAINS OIL COSTSInput pressure Direct energycomponentsEXCLUDED Indirect costs in other pricesHospitality · telecoms · transportRemain in U.K. core CPI CORE PRICE PRESSURECan outlast the direct fuel rise IF PRESSURE PERSISTSTighter policy in the staff simulation BITCOIN INFERENCEFinancing relief could be delayed
02 / Compare the estimated oil-to-core link
02 / Compare the estimated oil-to-core linkBefore 20212021 onward
The earlier sample's estimated response was about 0.01 percentage point and statistically insignificant.
Modelled core response, 2000 Q1--2020 Q4 SAME RELATIVE-OIL INFLATION INPUT+10percentage pointsNot a 10% oil-price rise2000 Q1--2020 Q4+0.01percentage pointcore inflation response00.15 ppStatistically insignificant
Modelled core response, 2000 Q1--2020 Q4 SAME RELATIVE-OIL INFLATION INPUT+10percentage pointsNot a 10% oil-price rise2000 Q1--2020 Q4+0.01percentage pointcore inflation response00.15 ppStatistically insignificant
The later sample's estimated response was about 0.14 percentage point. This is a pooled model estimate, not a forecast.
Modelled core response, 2021 Q1 onward SAME RELATIVE-OIL INFLATION INPUT+10percentage pointsNot a 10% oil-price rise2021 Q1 onward+0.14percentage pointcore inflation response00.15 ppStatistically significant
Modelled core response, 2021 Q1 onward SAME RELATIVE-OIL INFLATION INPUT+10percentage pointsNot a 10% oil-price rise2021 Q1 onward+0.14percentage pointcore inflation response00.15 ppStatistically significant
Persistent core pressure could delay financing relief for Bitcoin investors; the Bitcoin link remains an inference.
Pooled five-economy estimates through 2026 Q2; U.S. core PCE, core CPI elsewhere. Pre-2021 response is statistically insignificant. Forward paths are upper bounds, not official forecasts; the authors say current-shock second-round effects have not yet appeared. Dashed connector marks the inferred Bitcoin channel, not an observed response.
Sources and evidence
Sources
- Federal Reserve staff note, November 9, 2026
- ONS explanation of direct and indirect energy costs
- IMF working paper on monetary policy and crypto, 2023
Supporting facts
- A November 9, 2026 Federal Reserve staff note estimates a panel model for Canada, the euro area, Japan, the United Kingdom and the United States from 2000 Q1 through 2026 Q2, using US core PCE and core CPI elsewhere, with the post-pandemic period beginning in 2021 Q1. [1]
- In the Fed staff model, a 10-percentage-point increase in relative oil-price inflation is associated with about 0.14 percentage point higher core inflation under post-pandemic coefficients, versus about 0.01 percentage point before the pandemic, when pass-through was statistically insignificant. [1]
- The Fed staff study measures oil inflation using quarterly Brent prices in local currency relative to core inflation, and allows current and four lagged quarters of oil inflation to affect core inflation. [1]
- The UK's Office for National Statistics says core CPI excludes direct energy components but retains indirect energy costs embedded in prices such as hospitality, telecommunications and transportation. [2]
- The Fed staff authors describe their forward core-inflation paths as an upper bound rather than a central prediction, conditional on elevated post-pandemic persistence and pass-through continuing through 2028. [1]
- Assessing the current oil shock, the Fed staff authors say second-round effects have not yet materialized; their empirical model cannot distinguish a structural inflation change from more frequent or persistent global supply shocks, and the findings are not official forecasts. [1]
- In a separate structural simulation in the Fed note, stronger oil pass-through and inflation persistence require materially tighter monetary policy to contain inflation even as economic activity weakens. [1]
- An August 2023 IMF working paper finds that US monetary tightening reduces a common crypto price factor through a risk-taking channel, supporting a historical link between tighter policy and weaker crypto risk appetite. [3]
- Combining the Fed staff inflation risk with the IMF's monetary-policy evidence suggests a conditional Bitcoin headwind: persistent oil-driven core pressure could delay financing relief and keep risk appetite constrained, but neither source demonstrates an observed Bitcoin response to this study. [1] [3]
Method
The main diagram is schematic, using the ONS U.K. core-CPI explanation and the Fed/IMF conditional financing channel. Selectable regimes use reported responses for the same +10-percentage-point relative-oil-inflation input. Bars use a common zero-based 0--0.15-percentage-point scale; no new estimate or multiplier is calculated.
Scope
Pooled five-economy estimates through 2026 Q2; U.S. core PCE, core CPI elsewhere. Pre-2021 response is statistically insignificant. Forward paths are upper bounds, not official forecasts; the authors say current-shock second-round effects have not yet appeared. Dashed connector marks the inferred Bitcoin channel, not an observed response.
Infographic by CryptoSlate
Bitcoin's risk runs through monetary policy
The Fed authors call their forward inflation paths an upper bound rather than a central prediction, assuming elevated persistence and pass-through continue through 2028. Their pooled estimates may also capture wider post-pandemic shocks rather than a lasting change in oil's influence. These are staff findings, not official U.S. inflation forecasts.
In a separate structural simulation, the Fed staff find that stronger oil transmission combined with more persistent inflation requires materially tighter policy even as activity weakens.
That creates a possible headwind for Bitcoin through investors' willingness to take risk. An August 2023 IMF working paper found that U.S. monetary tightening reduced a common crypto-price factor through this risk-taking channel.
The Bitcoin implication is an inference from the two studies: if oil sustains core-price pressure, it could delay financing relief and constrain risk appetite. The studies do not estimate a Bitcoin price response.
The BLS schedule lists the October CPI report for Nov. 10. Persistent core pressure accompanied by reduced easing expectations would support the financing-risk interpretation; sustained disinflation and improving easing expectations would weaken it.
-- Price
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like
Strategy spent more than twice as much on preferred buybacks as Bitcoin last week

Onramp Launches Business Bitcoin Accounts With Two-Person Withdrawal Approvals As Wrench Attacks Climb
Algorithmic Trading and Cryptocurrencies: How Do Robots React to Volatility?

Mark Moss: Bitcoin is at the Best Buying Opportunity, Expected to Reach Historic Highs in 2027
Any Bitcoin recovery faces a cash problem as Binance’s stablecoins fall to $32 billion

MARA Bitcoin Mining Costs Reach $62,862 Per Coin, With Electricity Costs at $39,674
IPS has 500 million USD trapped in Ueno Bank
Large Bitcoin Mining Farm Dismantled in Culiacán with 130 Equipment
Bitdeer Reports 89% Revenue Growth in Q3 to $320.7 Million

What Happened Today in the Crypto Market? A Review of the Most Important Cryptocurrency News (November 9, 2023)
HIVE Reports $78.7 Million Net Loss in Q2, GPU Cloud Business Signs $185 Million ARR
Bloomberg: With Democrats Regaining Control of Congress, Are Good Days Over for the Crypto Industry in Washington?
Hyperscale Data Sells Off Bitcoin Reserves, Accumulating Approximately $74.4 Million for Debt Repayment and AI Data Center Construction

Canaan Technology Reports $14.5 Million Revenue in Q3, Initiates $20 Million Stock Buyback Plan
大冰要抄底(专注交易) Predicts Bitcoin and Ethereum Market Trends
Trump Media adds 1,510 Bitcoin in Q3 as treasury reaches $1.17B
47% Top Tax Rate Approaches: Seven Tax Reduction Strategies for Australian Crypto Investors
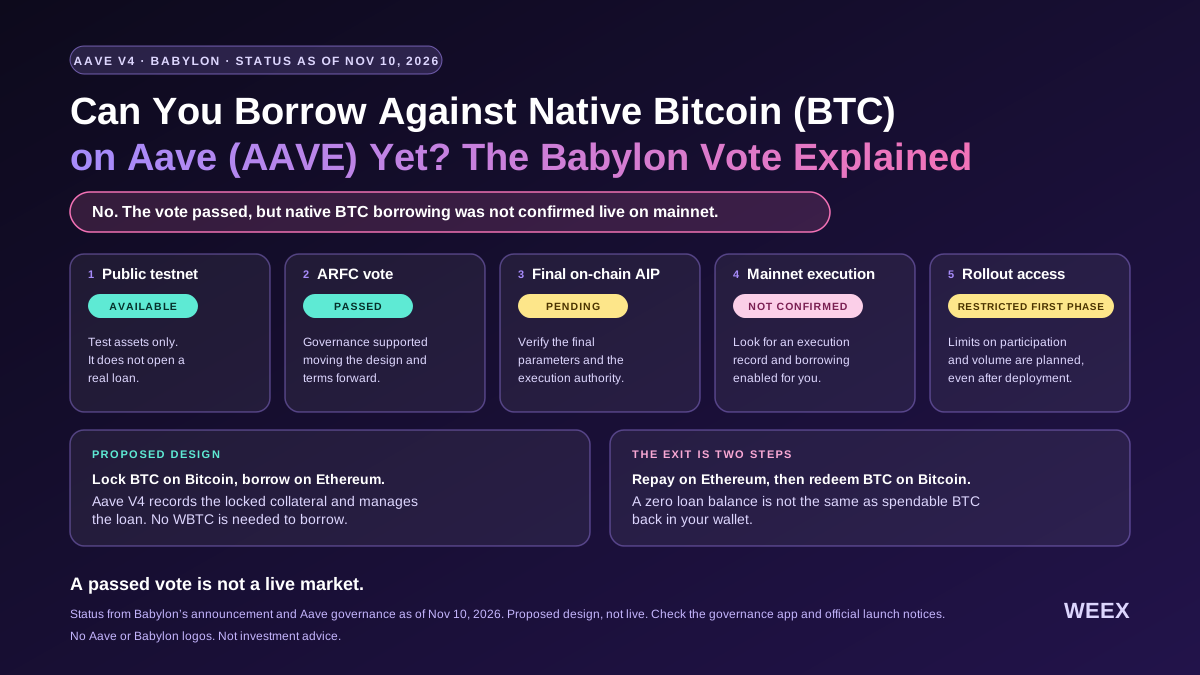
Can You Borrow Against Native Bitcoin (BTC) on Aave (AAVE) Yet? The Babylon Vote Explained
Can you borrow against native Bitcoin on Aave yet? See what the Babylon vote approved, what still needs to launch, and how BTC liquidation would work.

Kim & Chang Lawyer: "Excessive Responsibility Should Not Be Imposed on Stablecoin Issuers"
Mr&强 Analyzes Bitcoin and Ethereum Fluctuation Patterns

WEEX Exclusive:Middle East Easing Expectations Boost Stocks | WEEX Daily Brief (November 10, 2026)
On November 9 close, the S&P 500 and Dow both rose more than 2%. Middle East easing expectations pushed oil prices lower. Bitcoin and Ethereum spot ETFs saw net outflows last week. AVAX rose on reports of tokenized-stock clearing. PIEVERSE surged short-term. November 10 focus is October CPI, TSMC monthly sales data, CoreWeave earnings and others.

When is the launch date of Bitcoin Hyper? Testnet, tokens, and mainnet are separate milestones
Middle East Easing Expectations Boost Stocks | WEEX Daily Brief (November 10, 2026)
On November 9 close, the S&P 500 and Dow both rose more than 2%. Middle East easing expectations pushed oil prices lower. Bitcoin and Ethereum spot ETFs saw net outflows last week. AVAX rose on reports of tokenized-stock clearing. PIEVERSE surged short-term. November 10 focus is October CPI, TSMC monthly sales data, CoreWeave earnings and others.
Bitcoin non-empty wallets drop by 108700 amid retail capitulation
LNbits disables hosted Bitcoin services with no restart timeline
Bitcoin Spot ETF Sees Net Outflow of $201 Million for Three Consecutive Days
Ray Dalio Warns of Diminished Trust in U.S. Treasuries Amid Political Conflicts

BitPay Brings Apple Pay and Google Pay Checkout to Crypto Purchases

Four Security Strategies from the Wallet Theft Incident
Glassnode: Altcoin Trading Volume Returns to Normal Levels
Strategy spent more than twice as much on preferred buybacks as Bitcoin last week
Onramp Launches Business Bitcoin Accounts With Two-Person Withdrawal Approvals As Wrench Attacks Climb
Algorithmic Trading and Cryptocurrencies: How Do Robots React to Volatility?
Mark Moss: Bitcoin is at the Best Buying Opportunity, Expected to Reach Historic Highs in 2027
Any Bitcoin recovery faces a cash problem as Binance’s stablecoins fall to $32 billion
MARA Bitcoin Mining Costs Reach $62,862 Per Coin, With Electricity Costs at $39,674
Latest articles



Latest coin listings on WEEX


