
Crypto Tax in Vietnam: What Is Documented and What Remains Unsettled

 Prefer us on Google


The Government policy text published on 3 November 2025 records that Resolution 05/2025/ND-CP was issued and became effective on 9 September 2025, applying securities-tax rules to crypto-asset trading, transfers and business until a dedicated market tax policy exists; the Ministry of Finance announced on 30 March 2026 that it had issued guidance for those activities during the pilot. Public documents do not explain every type of crypto income in the same way.
What is documented?
Resolution 05 was issued and became effective on 9 September 2025, according to the Government policy text published on 3 November 2025. Article 4 says that tax policy for crypto-asset trading, transfers and business follows securities-tax rules until Vietnam has a tax policy for the crypto-asset market.
This matters because “there is no dedicated crypto tax law” does not mean “there is no tax duty”. The transitional rule is written into the resolution, while filing and evidence must be read with the tax text that applies to the person and the activity.
The Ministry of Finance announced on 30 March 2026 that it had issued Circular 32/2026/TT-BTC on 27 March 2026 to guide tax policy for crypto-asset trading, transfer and business activities in the pilot. Use the current text of that circular as the starting point for a transaction within its scope rather than applying a rate repeated online to every kind of crypto activity.
Why one rate cannot be assumed for everyone
Tax treatment depends on the taxpayer, activity, income event, cost records and transaction setting. An individual selling crypto, a business trading as part of its operations, an issuer and a service provider do not necessarily calculate or report in the same way. Resolution 05 dated 9 September 2025 also places tax responsibilities on issuers and requires service providers to collect and pay tax under tax law.
The Ministry announcement dated 30 March 2026 confirms Circular 32’s subject and issue date, but an announcement is not a complete treatment of every taxpayer scenario. Do not state that every personal transaction has one fixed rate without checking the circular, filing guidance and the underlying records.
Records worth keeping
Keep deposit, purchase, sale, transfer, withdrawal and fee history, the conversion value, transaction time and the legal entity providing the service. Resolution 05 dated 9 September 2025 requires a service provider to retain in Vietnam specified records of transactions, originators, beneficiaries, accounts, devices and access for at least ten years. A platform’s retention duty does not replace a user’s own evidence file.
Keep bank statements, deposit and withdrawal confirmations, fee documents, account reports and records showing how an asset was acquired. For transfers between personal wallets, record the source wallet, destination wallet, network, transaction reference and reason. Not every wallet transfer has the same tax character; records allow a professional to classify the event rather than guess from a label.
-- Price
What still needs separate checking?
The primary materials used here confirm the scope of Resolution 05 and Circular 32 as trading, transfers and crypto-asset business. In the retrieved public announcements, they do not provide a general conclusion for mining, staking, airdrops, gifts, decentralised finance, asset-for-asset swaps or activity through a platform outside the pilot’s scope. Those cases should not be called settled merely by saying “crypto is taxed like securities”.
The Ministry of Finance also has an official record for Circular 41/2026/TT-BTC concerning tax declaration, withholding, payment and finalisation on the crypto-asset market, as shown on the Government Portal document page accessed on 17 September 2026. Its title identifies a procedural subject, but readers should still check the full text, effective date and current applicability before filing.
A practical pre-filing check
- Identify whether you are an individual or organisation and whether the event is a sale, business activity, issuance or service. Record the activity date and the named rule you are applying.
- Compare Resolution 05/2025/ND-CP dated 9 September 2025 with Circular 32/2026/TT-BTC dated 27 March 2026. Do not substitute a social-media post for the original text.
- Match each transaction to money, asset, fee and conversion evidence. If data is missing, mark the gap rather than inventing a cost basis.
- Check Circular 41/2026/TT-BTC and current filing instructions if your records fall within the crypto-asset market. The Government Portal identifies its subject as declaration, withholding, payment and finalisation.
- Ask a tax professional about staking, mining, airdrops, gifts, asset-for-asset swaps and activity outside the expressly described scope. The answer must use your facts, not only a token name.
Frequently asked questions
Does crypto in Vietnam have a tax obligation?
There is a transitional obligation for activity within the scope of crypto-asset trading, transfers and business: Article 4 of Resolution 05 dated 9 September 2025 directs securities-tax treatment until a dedicated market policy exists. The filing method still depends on the taxpayer and transaction.
Can I use a rate I found online?
No. The Ministry of Finance announced Circular 32 on 30 March 2026, but the rate and calculation must be read in the full text and applied to your records. A rule for one transaction type does not automatically cover staking, gifts or asset-for-asset swaps.
What if I cannot classify my transaction?
Keep the records, do not delete history, and ask a tax professional how to classify the event. You can also read the custody and tokenised-asset guide and the network-record guide.
This article is general information, not legal or tax advice. Check the current text and consult a professional before filing.
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like
United States Dividend Fund (USDF) October 30 Announcement and October 31 Date: What to Verify Before Believing Either Claim
HOOD Q3 Earnings: Record $1.42B Revenue, So Why Did Crypto Revenue Fall 55%?
How Do Stablecoin Issuers Make Money? The Business Behind a $1 Token
Why Unitree Stock Jumped: JPMorgan Upgrade, Physical AI Timelines and What Investors Should Check
Tokenized Stocks Explained: What to Check Before You Trade
CLS Stock After Q3 Earnings: Revenue Up 83%, 2027 Outlook and What Investors Should Check
Which WEEX Moves Cost You Auto Earn Interest? 9 Actions Checked
How to Use WEEX Bubbles: A Practical Guide to Crypto Bubbles and Market Trends
SK Hynix Stock Before Q3 Earnings: Special Dividend Reports, HBM4 and What Investors Want to See on October 28
Corporate Actions for Tokenized Stocks: How Dividends, Splits and Mergers Are Handled
Your Auto Earn Floor: Why Your Lowest Balance Sets the Day's Pay
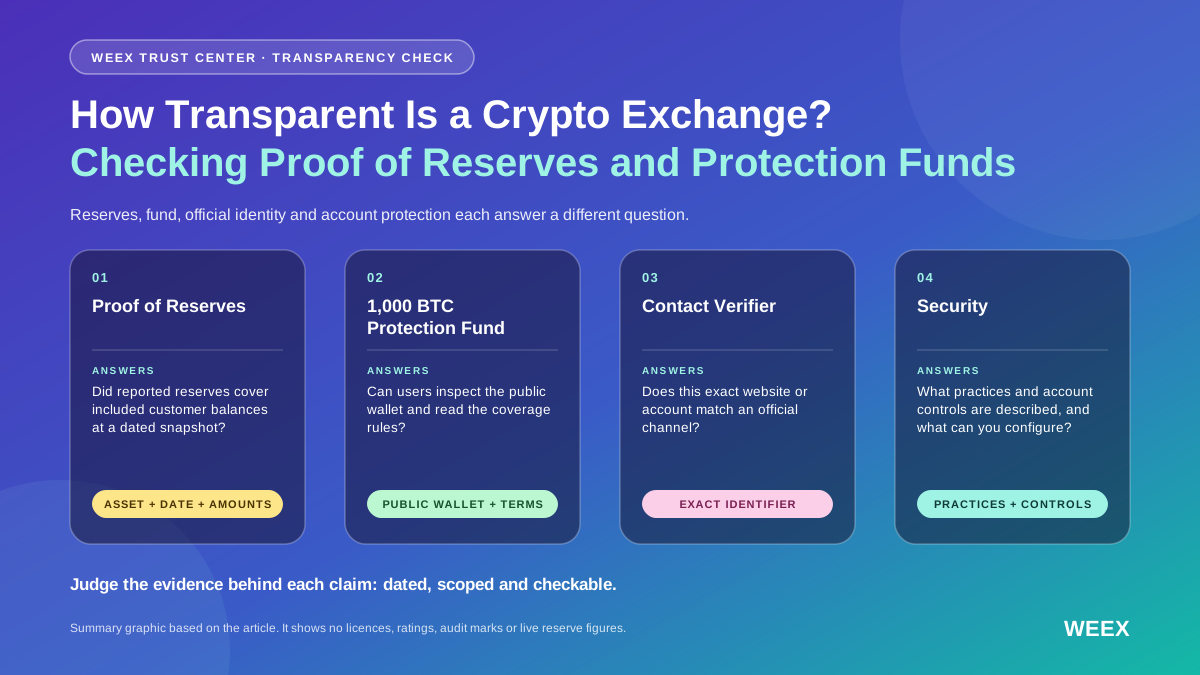
How Transparent Is a Crypto Exchange? Checking Proof of Reserves and Protection Funds On WEEX Trust Center
How to Check Your WEEX Convert History: Convert Records and Spot Transactions
Should Your Crypto Cash Buffer Sit in WEEX Auto Earn? The Math
BTC Funding Rate and Open Interest: What Each One Measures and How to Read Them Together
Stake ETH or Hold USDT on WEEX? The Price Move That Decides It
What Is Leverage Trading in Crypto? A Beginner’s Guide With Simple Examples
What Is Crypto Margin Trading? How It Works, How It Differs From Futures and What Can Go Wrong
Is My Pre-4.26.4 Qubic Wallet Unsafe? Recovery After the Network Restart
WXT Staking When Supply Shrinks: What Burns Add to Your Yield
The 17 October 2026 DBR Unlock: Six Allocations and deBridge's Vesting Schedule
Fake Crypto Payments: What to Check Before Handing Over Goods
What Is Leverage Trading? A Beginner’s Guide to Margin, Liquidation and Funding Fees
Is RSI a Good Indicator? How the Relative Strength Index Works, Its Limits and How Traders Use It
CXMT Stock Explained: What Is ChangXin Memory, Why It Fell on October 19 and What to Watch Next
The Cost of Idle USDT: What Unused Balances Miss Each Year
CRWV Stock Swings From -9.5% to +5.9%: Why CoreWeave Reversed
APR vs APY in Crypto: Why the Bigger Number Can Mislead You
Sandisk Stock After a 524% Run: Why SNDK Keeps Sliding Now
Best Crypto Miner for Beginners: What to Check on Cost, Power, Hashprice and Profit Before You Buy
United States Dividend Fund (USDF) October 30 Announcement and October 31 Date: What to Verify Before Believing Either Claim
HOOD Q3 Earnings: Record $1.42B Revenue, So Why Did Crypto Revenue Fall 55%?
How Do Stablecoin Issuers Make Money? The Business Behind a $1 Token
Why Unitree Stock Jumped: JPMorgan Upgrade, Physical AI Timelines and What Investors Should Check
Tokenized Stocks Explained: What to Check Before You Trade
CLS Stock After Q3 Earnings: Revenue Up 83%, 2027 Outlook and What Investors Should Check





