
Bitcoin’s year-end liquidity hopes face a projected $150 billion Treasury cash rebuild

 Prefer us on Google



The U.S. Treasury's Nov. 2 borrowing estimates put a possible year-end liquidity benefit for Bitcoin on a short timetable. Its cash assumptions imply a fourth-quarter drawdown followed by a larger rebuild early in 2027, a path that could reverse the Treasury-account contribution to bank reserves.
The department expects to borrow $618 billion in privately held net marketable debt during October--December, $10 billion less than estimated in August. But that lower headline owes to a larger inherited cash buffer. Strip out the opening-cash surprise and the borrowing requirement is $24 billion higher.
A larger cash buffer masks higher financing needs
Treasury entered the quarter with $984 billion in cash, compared with the $950 billion assumed in August. That extra $34 billion offsets the $24 billion increase in the cash-adjusted borrowing requirement, leaving the headline estimate $10 billion lower.
The end-December cash assumption remains $850 billion. Against the observed September endpoint, that implies a $134 billion decline across the whole fourth quarter. The projection covers the whole fourth quarter, including cash flows before Nov. 2.
The next quarter changes the direction. Treasury estimates $800 billion of borrowing for January--March 2027 and assumes an end-March cash balance of $1 trillion. Relative to the assumed December endpoint, that is a $150 billion rebuild.
If those assumptions are realized, the first-quarter refill would more than reverse the preceding quarter's projected cash drawdown through the Treasury-account reserve channel. The figures describe quarter-end assumptions; they do not provide a daily liquidity timetable.
Treasury's projected cash path reverses in Q1
Treasury's November 2 assumptions imply a $134bn whole-Q4 cash decline, then a $150bn Q1 rebuild. Only the September endpoint is observed.
TREASURY CASH / USD BILLIONS 1,000 900 800 $984bn $850bn $1,000bn −$134bn WHOLE Q4 CHANGE +$150bn Q1 REBUILD SEP. 30, 2026 Observed DEC. 31, 2026 Assumed MAR. 31, 2027 Assumed Cash axis begins at $800bn. Dashed path links quarter-end balances, not daily flows.
TREASURY CASH / USD BILLIONS 1,000 900 800 $984bn $850bn $1,000bn −$134bn WHOLE Q4 +$150bn Q1 REBUILD SEP. 30, 2026 Observed DEC. 31, 2026 Assumed MAR. 31, 2027 Assumed Cash axis starts at $800bn. Dashed path connects quarter-end balances; it is not a daily cash-flow forecast.
Follow the reserve channel
Follow the reserve channelQ4 2026 drawdownQ1 2027 rebuild
Projected whole-quarter cash decline: $984bn observed in September to $850bn assumed in December. A falling TGA supports reserves, all else equal.
Treasury account Bank reserves Cash −$134bn Support Net cash moves toward banks Reserve effect holds all else equal; other Fed balance-sheet changes can offset it.
Treasury account Bank reserves Cash −$134bn Support Net cash moves toward banks Reserve effect holds all else equal. Other Fed balance-sheet changes can offset it.
Projected cash rebuild: $850bn assumed in December to $1,000bn assumed in March. A rising TGA drains reserves, all else equal.
Treasury account Bank reserves Cash +$150bn Drain Net cash moves toward Treasury Reserve effect holds all else equal; other Fed balance-sheet changes can offset it.
Treasury account Bank reserves Cash +$150bn Drain Net cash moves toward Treasury Reserve effect holds all else equal. Other Fed balance-sheet changes can offset it.
If realized, Q1's cash rebuild would more than reverse Q4's Treasury-account support for reserves, all else equal.
December and March are assumptions, not realized cash balances. Q4 includes October and is not remaining release after Nov2. Other Fed assets and liabilities can offset reserves. No Bitcoin price effect is established.
Sources and evidence
Sources
- Treasury borrowing estimates, November 2, 2026
- Federal Reserve liabilities: Treasury-account reserve channel
Supporting facts
- Treasury ended September with $984 billion cash against a prior $950 billion assumption. The $34 billion opening-buffer increase offsets the $24 billion cash-adjusted borrowing increase to produce the $10 billion headline reduction. [1]
- The $850 billion end-December cash assumption implies a $134 billion decline across the whole fourth quarter from the observed $984 billion September endpoint; it is neither a completed reserve injection nor an estimate of cash still to be released after November 2. [1]
- For January--March 2027, Treasury estimates $800 billion of privately held net marketable borrowing and a $1 trillion end-March cash balance, implying a $150 billion rebuild from the assumed December endpoint. [1]
- If the cash assumptions are realized, Q1's $150 billion rebuild would more than reverse Q4's projected $134 billion drawdown in the Treasury-account contribution to reserves, all else equal; other balance-sheet changes could offset it, and the forecasts establish no Bitcoin price response. [1] [2]
- Treasury payments from its Federal Reserve account increase depository institutions' balances, all else equal; receipts into Treasury's account drain them. Federal Reserve assets, currency, reverse repos and other deposits also affect reserves. [2]
Method
USD billions. Verified arithmetic: 850−984=−134 across Q4; 1000−850=+150 across Q1. Cash chart maps 800--1000 linearly and explicitly starts at 800. Dashed segments join endpoints only. Reserve diagrams describe conditional accounting direction, not measured transfers or Bitcoin demand.
Scope
December and March are assumptions, not realized cash balances. Q4 includes October and is not remaining release after Nov2. Other Fed assets and liabilities can offset reserves. No Bitcoin price effect is established.
Infographic by CryptoSlate
CryptoSlate's Nov. 2 setup coverage examined the forthcoming release using August assumptions. The new estimates add the cross-quarter reversal and show why the smaller borrowing headline should not be read as weaker underlying financing needs.
The Federal Reserve's accounting explanation describes the channel. When Treasury pays from its account at the central bank, funds move into a depository institution's account, increasing bank reserves, all else equal. Receipts into Treasury's account work in the opposite direction.
A falling Treasury General Account, or TGA, can therefore support reserves. The eventual total also depends on Fed assets and other liabilities, including currency, reverse repos and other deposits.
The net cash movement already reflects financing, receipts and spending. Counting debt issuance as an additional reserve drain on top of that same net TGA change would count the financing component twice.
The latest H.4.1 release, published Oct. 29, showed reserves averaging about $2.89 trillion in the week ended Oct. 28, down $69 billion from the prior weekly average. Treasury's account averaged $1 trillion, up $48 billion.
The Wednesday TGA balance was a separate observation: $1.02 trillion on Oct. 28.
Fed operations can also change the outcome. For Oct. 15--Nov. 13, the New York Fed planned approximately $15 billion in reinvestment purchases and no reserve management purchases. Reinvesting principal is distinct from expanding the portfolio. Future reserve management purchases remain conditional on reserve and money-market conditions.
Funding prices still have to confirm the benefit
The latest overnight observations available early Nov. 3 were for Oct. 30. The New York Fed's reference-rate data put the secured overnight financing rate, or SOFR, at 3.95% and the effective federal funds rate at 3.88%.
SOFR was five basis points above the Fed's 3.9% interest rate on reserve balances, which its Oct. 28 implementation note maintained effective Oct. 29. Effective federal funds remained inside the 3.75%--4% target range. The observation predates the Treasury release.
For Bitcoin's liquidity thesis to strengthen, a realized cash decline would need to translate into easier reserve and funding conditions, then meet actual demand for the asset.
Treasury's additional financing details are due Nov. 4 at 8:30 a.m. The issuance mix and settlement path will help define how the aggregate plan reaches markets. Until those details and subsequent cash flows arrive, the new forecast supports a possible temporary funding benefit, with a larger planned cash rebuild already on the horizon.
-- Price
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like
Has Wall Street Broken the Mechanism That Made Bitcoin Soar?
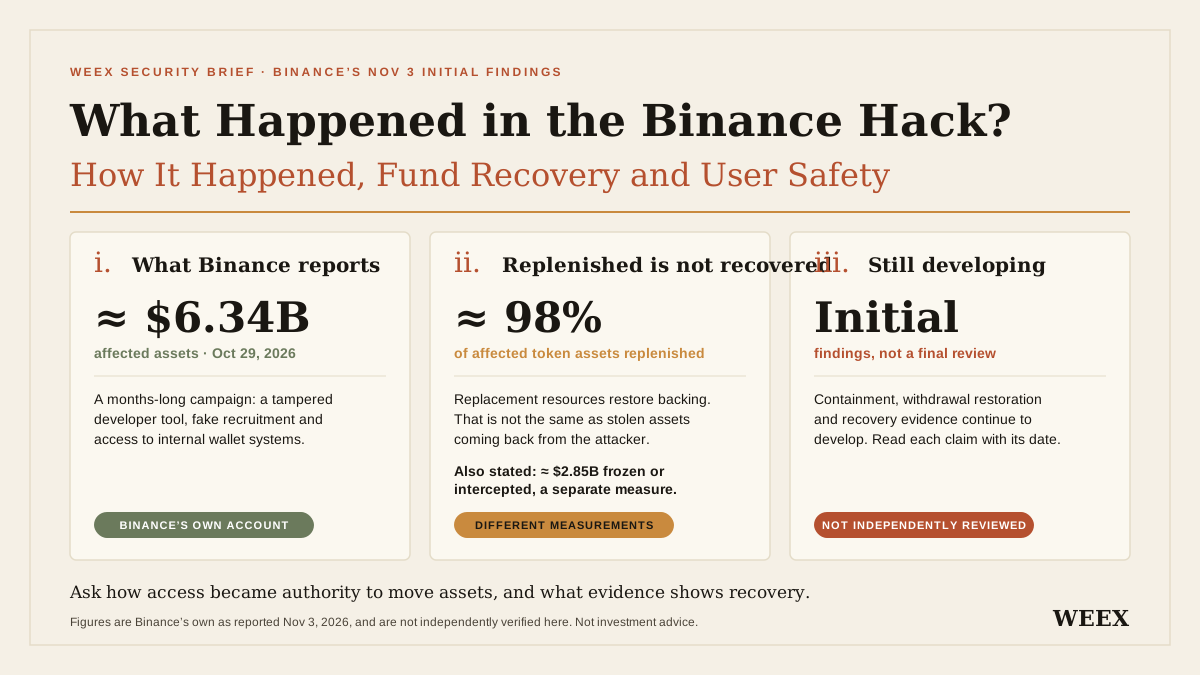
What Happened in the Binance Hack? How It Happened, Fund Recovery and User Safety
What happened in the Binance hack? Review the attack timeline, latest fund replenishment, recovery limits and practical steps to protect your account.
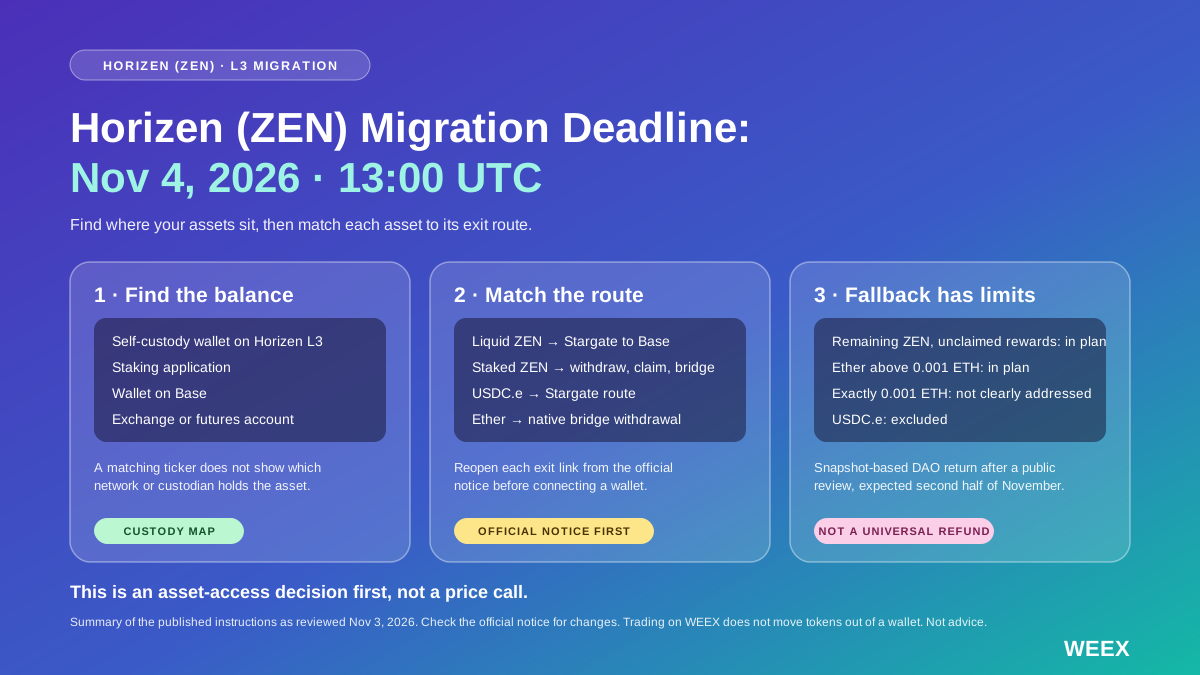
Horizen (ZEN) Migration Deadline: What to Move Before November 4 and What Happens If You Miss It
Horizen (ZEN) migration closes November 4. Check asset-specific bridge routes, wallet requirements, recovery exclusions and what to do if you miss it.
DMG Says Client Assets Are Secure and Highlights Layered Transaction Controls
Solana study finds wider spreads outside aggregators at five of six sampled pools
Crypto: Gate Freezes Two Accounts Linked to Binance Hack
BlackRock’s Ethereum fund sheds 580K ETH as monthly exits mount
How T7X Is Building the Infrastructure for a New Era of Capital Markets
The End of the Seasonality Myth. Why September and October Surprised Investors?
Hong Kong plans stablecoin trials for tokenized government debt
Ownership of Bitcoin in the Qian Zhimin Case and Victim Compensation
Polygon expands US banking access to Solana's 15 billion stablecoin market
Sui Puts Enforced Spending Limits at the Center of Its AI-Agent Design
Apple Reclaims Top Market Cap as Silver Nears $50: WEEX TradFi Market Brief
Vitalik's Latest Thoughts: We Need a Digital Minimalism Movement
RLUSD supply fell 29% on XRPL. One XRP trading pool barely changed
Mercado Bitcoin Plans Sui Asset Access in Brazil With Lending and Tokenization Links
Bitcoin Volatility Calendar: Which Events Really Shake the Market?

The decline of gold could signal further tensions, according to Peter Schiff
Bitcoin Turns 18; Will Satoshi's Legacy Stand the Test of Time?
Polygon Completes Coinme Acquisition to Expand Regulated Fiat Payment Rails
The Need for Institutionalization of Market Makers Between Liquidity Provision and Price Manipulation
Chainlink Launches CustodySync With Anchorage to Link Custody and DeFi Loans

CDI was the only refuge in October: what this reveals
Lagarde to leave ECB with Europe’s tokenized-finance blueprint still undecided
Polkadot OpenGov #1961: dotUSD Supply Bug and $1.3M Treasury Loss Explained
Cryptocurrency Market Makers: Distinguishing the Real from the Fake – Tiger Research
Hanwha Investment & Securities Partners with Chainlink to Build Global RWA Tokenization Platform
Controversy over Gold: BCRA Revealed How the Operation with the Metal Was Questioned by AGN
Silicon Valley shifts AI funding to crypto using an Ethereum ICO blueprint
Has Wall Street Broken the Mechanism That Made Bitcoin Soar?
What Happened in the Binance Hack? How It Happened, Fund Recovery and User Safety
What happened in the Binance hack? Review the attack timeline, latest fund replenishment, recovery limits and practical steps to protect your account.
Horizen (ZEN) Migration Deadline: What to Move Before November 4 and What Happens If You Miss It
Horizen (ZEN) migration closes November 4. Check asset-specific bridge routes, wallet requirements, recovery exclusions and what to do if you miss it.
DMG Says Client Assets Are Secure and Highlights Layered Transaction Controls
Solana study finds wider spreads outside aggregators at five of six sampled pools
Crypto: Gate Freezes Two Accounts Linked to Binance Hack


