
Tesla Stock's Robotaxi Network Story Is Dead: JPMorgan Says the Money Flows to Tesla Alone

 Prefer us on Google

Tesla stock built part of its long-term valuation story on a promise Elon Musk made as far back as 2016: buy a car, enroll it in a shared ride network, and let it earn money while you sleep. JPMorgan just published the numbers that retire that promise.
Tesla stock's actual robotaxi economics, according to a note analyst Rajat Gupta circulated last week, look almost nothing like the passive income pitch that shaped how a generation of buyers thought about owning a Tesla. Nearly all the money, it turns out, stays with the company.
What JPMorgan Actually Projected
Gupta's note forecasts roughly $320 billion in Tesla robotaxi revenue by 2035. The specific breakdown is what makes this note newsworthy rather than just another price target update: approximately $314 billion of that total, close to 98%, would come from a fleet Tesla owns and operates directly. Customer owned vehicles enrolled in a shared network, the original "Tesla Network" concept, would contribute only about $5 billion, a figure small enough to function as a rounding error next to the company-owned total.
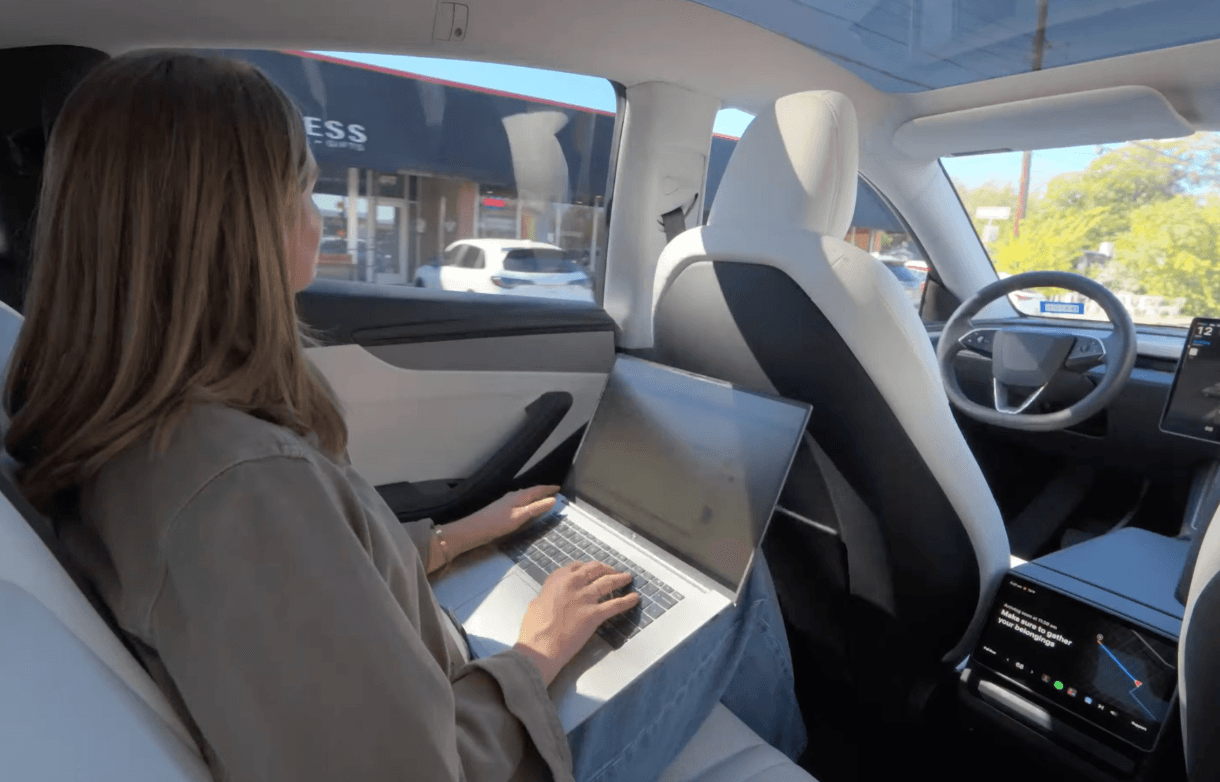
That framework effectively repositions Tesla's robotaxi business entirely. Rather than an asset-light software platform that takes a cut of transactions from a distributed network of individual owners, similar to how ride hailing apps operate, Gupta's model describes something closer to a vertically integrated mobility operator, a scaled up version of Waymo rather than the peer to peer vision Musk originally sold.
Why the Original Pitch Mattered So Much
Understanding why this reframing carries weight requires remembering how central the passive-income promise was to Tesla's public narrative for close to a decade. At the company's 2019 Autonomy Day, Musk told investors and owners directly that vehicles would be added to a ride hailing app modeled on Uber, letting individual owners earn money whenever their car wasn't in personal use. By 2020, he was predicting Tesla robotaxis would be running within a year, a timeline that, like several before it, didn't materialize.
Specific dollar figures circulated for years around what this income could actually look like. Musk suggested a Tesla operating roughly ten hours a day in a busy urban market could generate meaningful annual income at rates around 65 cents per mile, with some estimates putting potential owner earnings between $10,000 and $50,000 per year depending on usage and location. Those numbers shaped purchase decisions for buyers who viewed Full Self-Driving capability as a future income-generating asset rather than simply a convenience feature, which is precisely why a note concluding that structure contributes closer to $5 billion than $300 billion carries real weight beyond a routine analyst revision.
What Tesla Actually Built Instead
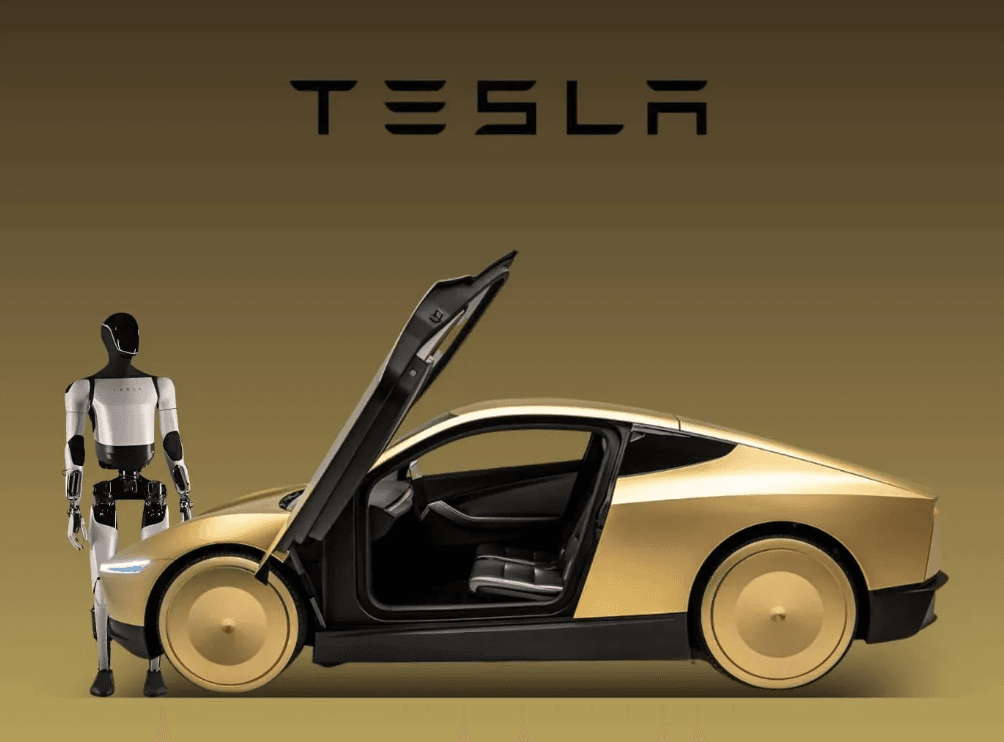
The gap between the original pitch and JPMorgan's projection reflects what Tesla has actually built over the past several years rather than a hypothetical concern. Until recently, Tesla kept its robotaxi business firmly in house, operating its own fleet, first using Model Y vehicles and now the purpose built Cybercab, rather than opening the platform to individual owners. Robotaxi service currently spans seven US metro areas, and Cybercab production has begun at Gigafactory Texas, according to reporting cited by 247 Wall St and Yahoo Finance.
There's a notable wrinkle worth mentioning directly: Tesla has recently opened the door to third party robotaxi operators, a shift the company frames as helping build out its network. But this development is distinct from the original owner passive income model Musk pitched for nearly a decade. Third party fleet operators are a different structure entirely from individual Tesla owners enrolling their personal daily-driver vehicles, and nothing in recent reporting suggests this change meaningfully alters JPMorgan's underlying math about where the bulk of robotaxi revenue actually flows.
-- Price
Why This Lands Alongside Genuinely Strained Financials
JPMorgan's projection isn't landing in isolation from Tesla's current financial picture, and the timing is worth noting directly. Tesla reported fiscal second quarter 2026 revenue of $28.24 billion, up 25.5% year-over-year, but non-GAAP earnings per share of $0.33 missed the $0.54 consensus estimate. Operating margin compressed to just 1.4% for the quarter, and free cash flow swung negative to roughly negative $1.09 billion, according to figures reported by 247 Wall St and AOL. CFO Vaibhav Taneja has guided 2026 capital expenditures above $25 billion specifically to fund fleet expansion, underscoring just how capital intensive the company owned model JPMorgan describes actually is compared to the asset light network Musk originally pitched.
Wall Street's earnings estimates have moved accordingly. The Street's 2026 EPS consensus has drifted from $2.11 two months ago down to $1.77, absorbing 18 downward revisions against just 7 upward revisions over the trailing 30 days. Tesla stock currently carries a forward P/E of 152, a multiple that requires investors to underwrite a substantial amount of future growth given where current earnings actually stand.
Why JPMorgan Still Isn't Bearish on the Stock
Despite dismantling one of Tesla's longest running narratives, JPMorgan's own positioning on the stock isn't straightforwardly negative. The bank upgraded Tesla from "underweight" to "neutral" back in June 2026, lifting its price target to $475 per share from a prior $145, a 227% increase. That combination, retiring a specific bullish narrative while still raising the price target substantially, reflects a real tension in how the bank is actually valuing the stock: the target implies meaningful potential appreciation from where shares traded before the upgrade, while a "neutral" rather than "overweight" rating signals the stock isn't obviously cheap at current levels either.
That nuance matters for reading this note correctly. JPMorgan isn't arguing Tesla's robotaxi business lacks value. It's arguing the value accrues differently than the company's own public messaging suggested for years, concentrated in Tesla's balance sheet and operating fleet rather than distributed across a network of individual vehicle owners who bought in partly on that promise.
What This Means Going Forward
None of this confirms Tesla's robotaxi business will actually reach $320 billion in revenue by 2035, a projection nearly a decade out that depends on execution, regulatory approval, and competitive dynamics against rivals like Waymo, which JPMorgan's own framing explicitly invokes as the more accurate comparison point going forward. What the note does confirm is a structural shift in how the most detailed available third-party analysis expects Tesla's robotaxi economics to actually work, regardless of what the original pitch to buyers promised years earlier.
For current and prospective Tesla owners who purchased Full Self-Driving capability with the passive-income story in mind, this note represents the clearest quantification yet of how far that specific outcome now appears from where the business has actually landed.
Where Tesla Stock's Next Catalysts Actually Show Up
Everything in JPMorgan's note is a projection, not a confirmed outcome, and the gap between what Musk promised in 2019 and what the company has actually built since gives a sense of how much these long-range robotaxi forecasts can shift before 2035 actually arrives.
TSLA is available on WEEX as part of its Stock Spot 2.0 lineup, funded directly with USDT, which is a practical consideration specifically because a story this long-dated tends to move in response to nearer-term data points, quarterly fleet expansion numbers, regulatory approvals in new metros, or updated analyst notes revising the fleet versus network split further, rather than in one single confirming or denying event. Trading on WEEX is backed by a publicly disclosed 1,000 BTC protection fund, giving traders a verifiable layer of security while positioning around a name whose current 152 forward P/E already prices in a considerable amount of the very robotaxi growth JPMorgan just reframed. TSLA is available on WEEX now for anyone looking to act on how that reframing continues to play out in the stock's price.
Conclusion
JPMorgan's projection that roughly 98% of Tesla's future robotaxi revenue will flow through a company owned fleet, rather than the individual owner network Musk pitched as far back as 2016, effectively retires one of Tesla stock's longest-running narratives. The reframing arrives alongside genuinely compressed near-term financials, a 1.4% operating margin and negative free cash flow in the most recent quarter, even as JPMorgan itself maintains a substantially higher price target than before its June upgrade. The story hasn't necessarily gotten worse for Tesla as a business. It's simply been quantified in a way that looks very different from what individual owners were originally told to expect.
FAQ
1. What did JPMorgan actually project about Tesla's robotaxi business?
Analyst Rajat Gupta projected roughly $320 billion in Tesla robotaxi revenue by 2035, with approximately $314 billion, about 98%, coming from a Tesla owned and operated fleet rather than individual customer-owned vehicles.
2. What happened to Tesla's original "Tesla Network" passive income promise?
Under JPMorgan's model, customer owned vehicles enrolled in a shared network would contribute only about $5 billion of the $320 billion total, a fraction of what Musk originally pitched to buyers starting as far back as 2016.
3. Is JPMorgan bearish on Tesla stock overall despite this note?
No. The bank upgraded Tesla from underweight to neutral in June 2026 and raised its price target to $475 from $145, even while reframing how robotaxi revenue is expected to actually flow.
4. How is Tesla's current financial performance factoring into this story?
Tesla's Q2 fiscal 2026 operating margin compressed to 1.4%, free cash flow turned negative at roughly $1.09 billion, and non-GAAP EPS missed consensus, even as capital expenditures are guided above $25 billion to fund fleet expansion.
5. Has Tesla opened its robotaxi network to third parties?
Yes, recently, though this involves third party fleet operators rather than individual owners enrolling personal vehicles, a structurally different arrangement from the original passive income pitch JPMorgan's projection addresses.
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like

WEEX Exclusive:ISM and Dell Drive the AI Trade | WEEX TradFi Daily(Sep. 1, 2026)

ISM and Dell Drive the AI Trade | WEEX TradFi Daily(Sep. 1, 2026)
This brief focuses on institutional crypto allocation, U.S. manufacturing data, Dell earnings as a test of AI server demand, and Tesla’s autonomy-driven support for technology risk appetite. Since oil was already covered in yesterday’s brief, today’s report avoids repeating the crude-oil theme. NVIDIA, China technology shares, South Korean semiconductor exports and Broadcom’s market-highlight item have been removed, with Broadcom kept only in Today’s Preview.

Can Anthropic Become the FTX of AI?

Direct Access to US Stock Market Liquidity: Bitget Wallet Integrates Reality to Create "On-Chain Wall Street"

Solutions to AI Apocalypse Exist: Jensen Huang Proposes 'Engineering Control' and Musk Suggests 'Peer Review'

Grayscale: In the Age of AI, Financial Privacy is Becoming a Core Issue for Crypto

Market Value Reaches $50 Million, NFT Floor Price Hits $30, What Are The Returns of The Standard Reserve?

Crypto: Grayscale Targets $2 Trillion in Boomer Flows

New Fire Research Institute: The Arrogance of Traditional Trusts is Losing the Next Generation of High-Net-Worth Crypto Clients

Exploit rsETH on Ethereum: a Safe wallet loses $7.73 million

Goldman Sachs Predicts RMB Will Appreciate to 5.5 in Five Years: What Should You Do?

Trump Agreed to Crypto Income Limits — Will It Be Enough to Save the CLARITY Act Today?
Trump agreed to crypto ethics limits in the CLARITY Act, but his existing $1.4B in crypto income is grandfathered in. Here's the full breakdown.

Bitcoin vs Fed 2026: Can BTC Survive Higher Rates?

CLARITY Act Odds Crash to 16%, Then Rebound to 31%: Inside the Ethics Fight That Won't Stay Settled
CLARITY Act odds crashed to 16%, then rebounded on Trump's ethics compromise — only for new opposition to emerge. Here's the full odds timeline explained.
Justin Sun Sues Trump's World Liberty Financial: What It Means for the CLARITY Act's Ethics Fight
Justin Sun sued Trump's World Liberty Financial over frozen tokens, and WLFI countersued for defamation. Here's what the fight means for the CLARITY Act.
AMD Stock Falls Below $500 as CEO Lisa Su Sells Shares: Here's What Her Filing Actually Shows
AMD stock dropped below $500 the same day Lisa Su's SEC filing surfaced but the sale was scheduled months ago and had nothing to do with the drop.

Why Did 7 Senate Democrats Say Trump's Crypto Ethics Deal 'Falls Short' Before Today's Vote?
7 Senate Democrats called the CLARITY Act's ethics language insufficient. Here's each senator's specific objection and whether it's actually been fixed.

Nvidia Wants to Fund the Same Company Warning About AI's Pace: A Real Contradiction, or Not?
Anthropic warns the world to slow down AI. Nvidia wants to fund its IPO anyway, a tension that says more about hedging than hypocrisy.

Can SKY Reach $0.10 in 2026? Standard Chartered Turns Bullish
Bitcoin self-custody creates a massive cost-basis blind spot on your 2026 crypto tax forms
The End of an Ideal: Why the Crypto Industry is Heading Towards Homogenization?

Why is Gold Still 'Stuck' Despite Soaring Rate Hike Expectations and US Treasury Yields Breaking 5%?
Proposed stablecoin rules might guarantee your dollar while making you wait a week to spend it
BlackRock and Visa Join Forces! A Comprehensive Overview and Practical Guide to Circle's Arc Ecosystem

IOSG: The Expensive Ticket of HIP-3, A Moat That Can't Be Bought

Did LayerZero lose the private key that allows the creation of stablecoins for the State of Wyoming?

5% Rate, Brent at $110: The Fed Stuck Before Wednesday
TRX ETF Launches, TRON's Ambitions Go Beyond "US Stock Compliance"

Bitcoin Direct Ownership vs Treasury Stocks: Which is the After-Tax Profit Winner?…Bitplanet Compares Investment Structures
Satoshi Mystery: Will It Lead to Participation Rewards? K1 Research Analyzes Meme Bitcoin
WEEX Exclusive:ISM and Dell Drive the AI Trade | WEEX TradFi Daily(Sep. 1, 2026)
ISM and Dell Drive the AI Trade | WEEX TradFi Daily(Sep. 1, 2026)
This brief focuses on institutional crypto allocation, U.S. manufacturing data, Dell earnings as a test of AI server demand, and Tesla’s autonomy-driven support for technology risk appetite. Since oil was already covered in yesterday’s brief, today’s report avoids repeating the crude-oil theme. NVIDIA, China technology shares, South Korean semiconductor exports and Broadcom’s market-highlight item have been removed, with Broadcom kept only in Today’s Preview.
Can Anthropic Become the FTX of AI?
Direct Access to US Stock Market Liquidity: Bitget Wallet Integrates Reality to Create "On-Chain Wall Street"
Solutions to AI Apocalypse Exist: Jensen Huang Proposes 'Engineering Control' and Musk Suggests 'Peer Review'
Grayscale: In the Age of AI, Financial Privacy is Becoming a Core Issue for Crypto
Contents
Latest articles


Latest coin listings on WEEX


